


In international rankings, Ulm University is one of the world's leading universities in the field of actuarial science. [press release]
Numerous research projects and theses have been awarded prizes in recent years.


Welcome at the Institute of Insurance Science!
In international rankings, Ulm University is one of the world's leading universities in the field of actuarial science. [press release]
Numerous research projects and theses have been awarded prizes in recent years.
We offer a comprehensive study program focusing on actuarial science, insurance, and risk management in the study programs Finance, Economics, and Mathematics and Management, which integrates all six basic knowledge exams for actuaries (DAV).
The high quality and practical relevance of the Ulm Actuarial Program is confirmed by the testimonials of numerous graduates.
News
On 7 November 2026, Prof. Dr. An Chen, Head of the Institute of Insurance Science at Ulm University, gave a public lecture on the future of retirement provision. The event took place at the Studio der Sparkasse Ulm as part of “Wissen erleben – Uni Ulm in der Stadtmitte”, the 35th lecture series organised by the Ulmer Universitätsgesellschaft.
In her talk, “Länger leben – wie bleibt die Rente sicher?”, she explained why demographic change and rising life expectancy are putting pressure on pension systems and how retirement savings can be turned into a lifelong income. She introduced modern tontines, drawing on her research into the “Tonuity” model. She also discussed how supplementary funded pensions could contribute to pension reform and what challenges remain.
A lively discussion with the audience followed. Sincere thanks to Manfred Oster, former Chair of Sparkasse Ulm’s Management Board, as well as to Stefan Quintus, the Ulmer Universitätsgesellschaft and Sparkasse Ulm!

The Institute of Insurance Science is proud to announce that our chair, Prof. Dr. An Chen, has been named the recipient of the 2026 HEC Lausanne I.N.S.P.I.R.E. Award.
Presented on the recommendation of HEC Lausanne’s Department of Actuarial Science, this distinction recognises her outstanding and inspiring career as a woman in science.
Standing for “INspiring Success: Promoting Inclusion, Research and Excellence,” the award honours a career that exemplifies academic excellence and perseverance.
The award ceremony will take place at HEC Lausanne on 4 November 2026.
On this occasion, Prof. Dr. An Chen will give a presentation entitled “Researching Uncertainty, Building Communities: Sustainable Finance, Risk, and Academic Engagement.”
We warmly congratulate An on this well-deserved recognition!
More information: https://www.unil.ch/news/en/1792739057783

From 20 to 22 September 2026, the second workshop of DFG Research Unit FOR 5583, “Asset Allocation and Asset Pricing under Regulatory Uncertainty,” took place at Schloss Reisensburg.
Principal investigators and early-career researchers presented progress across the research projects and explored opportunities for collaboration. Prof. Dr. An Chen, spokesperson of the research unit, and postdoctoral researcher Dr. Ilaria Stefani introduced sustainability-linked bonds as a potential research topic connecting regulatory uncertainty, sustainable finance, asset allocation and asset pricing.
Breakout sessions focused on regulatory uncertainty, ESG, textual analysis and regime switching. Participants developed and presented new research ideas, strengthening interdisciplinary collaboration within the research unit.
The research unit is funded by the German Research Foundation (DFG). [More information]

On 9 and 10 July 2026, we were delighted to welcome colleagues from Fudan University for the 7th edition of our joint symposium. The event continued a long-standing research partnership between the two universities. Prof. Michael Weber, President of Ulm University, and Prof. Robert Stelzer, Dean of the Faculty of Mathematics and Economics, opened the event.
Across four scientific sessions, senior academics, early-career researchers and PhD students from both institutions presented their latest research and exchanged ideas in finance and insurance. A programme of social and cultural activities complemented the academic discussions.
The accompanying video captures highlights from the presentations, discussions and cultural activities, offering a glimpse into how researchers from Ulm and Fudan continued their exchange beyond the academic sessions.
On 21 May 2026, Prof. Dr. An Chen participated in a lunchtime meeting with young women researchers, organised by the Gender Equality Office of Ulm University.
Drawing on her academic career across different disciplines, institutions and countries, she shared insights into academic career development, emphasising the importance of recognising opportunities, building an independent research profile, developing supportive networks and balancing ambition with sustainability.
An open discussion followed on confidence, family, career decisions and structural challenges faced by early-career researchers. Special thanks go to Clarissa Gobiet and Dorothea Güttel from the Gender Equality Office for organising the meeting.

On 8 May 2026, the Institute of Insurance Science participated in Ulm University's Langer Abend der Wissenschaft, introducing visitors to actuarial science and its role in understanding and managing future risks.
At the institute's booth, researchers explained how mathematics, economics, statistics, finance and data science contribute to insurance and risk management. Discussions with prospective students, families and senior visitors covered study and career opportunities, retirement planning and long-term financial security.
An interactive quiz on insurance and actuarial science invited visitors to test their knowledge and provided opportunities for further discussion, highlighting the relevance of actuarial research to everyday life.

From 18 to 20 March 2026, the first Future Actuarial Research (FAR) Workshop took place at Schloss Reisensburg. Prof. Dr. An Chen organised the event on behalf of the Research & Transfer Committee of the German Society for Insurance and Financial Mathematics (DGVFM).
The workshop brought together PhD candidates and postdoctoral researchers in actuarial science for full-paper sessions, short presentations and detailed feedback from experienced professors. Senior talks by Prof. Mogens Steffensen and Prof. Mario Wüthrich offered insights into academic career development.
By encouraging exchange between early-career and senior researchers, the workshop supported the development of a sustainable research community in actuarial science.

On 24 February 2026, the 14th Joint IVW–ifa Workshop brought together researchers and practitioners in actuarial science. The workshop was jointly organised by us and the Institut für Finanz- und Aktuarwissenschaften (ifa). Prof. Hajo Zwiesler also attended.
The programme featured contributions from Tom Pohlschmidt on voluntary risk testing in insurance, Reza Dastranj on linearising mortality models using PCA and GEEs, Tobias Baur on interpretable ensembles, Philipp Schulz on stochastic mortality model selection, and Mingyu Liu on optimal fee schedules for advance tax rulings.
The workshop provided a platform for discussing recent methodological developments and their practical applications in actuarial science.
Peter Werner (M. Sc. Economics) received the VFVH Excellence Award 2026 for his master's thesis entitled "Implikationen der Insurance Recovery and Resolution Directive (IRRD) für Versicherungsunternehmen und das Sicherungssystem der deutschen Lebensversicherer", supervised by PD Dr. Stefan Schelling.
The award is presented annually by the Association for the Promotion of Insurance Science in Hamburg (VFVH) in recognition of outstanding academic work in insurance science.
Many congratulations to Peter!
Find more information here.

We are very pleased to share two in-depth presentations on current topics here and with the actuarial community through actuview (the first permanent and international media platform for actuaries):
Interpretable Ensembles: Enhancing Claim Frequency Modeling with External Socioeconomic Factors
Tobias Baur
On the afternoon of 27 November, we welcomed a group of highly motivated bachelor's and master's students to the Women's Research Afternoon at Villa Eberhardt. The event brought together female professors and researchers from Economics and Mathematics for an inspiring afternoon of exchange, learning and connection at all stages of the academic journey.
Throughout the panels, small-group workshops and evening networking session, participants gained honest insights into academic career paths and explored research opportunities in an encouraging and supportive environment.
Special thanks go to my dear colleagues, PD Dr Luna Bellani, Prof Dr Anna Dall`Aqua and Prof Dr Sandra Ludwig, whose insights enriched the program.
Sincerest thanks also go to Madlen Atzen, Helen Kafka, Miriam Ni Chobhthaigh, Sabrina Rittinger, Natalie Rupp, Sandra Schmeller and Chiara Schwenke for their dedicated and inspiring contributions.
We’re excited to announce that the DFG Research Unit “Asset Allocation and Asset Pricing under Regulatory Uncertainty” (FOR 5583) has officially kicked off at Schloss Reisensburg in Günzburg!
Under the leadership of Spokesperson An Chen from Ulm University, the all-women team of Principal Investigators (PIs) have set a tone of inspiration, support, and collaboration from day one. We’re looking forward to all the ways we will work together, learn from one another, and push the boundaries of our research.
The event wasn’t all work, though. The team also made sure to enjoy themselves with lively dinners and late-night board games. Both the PIs and our PhD researchers and postdocs had a great time and left feeling energized and motivated for the exciting work ahead.
Official website of the Research Unit: Link
LinkedIn: Link


We’re thrilled to announce that the German Research Foundation (DFG) is funding the new research unit (DFG Forschergruppe) “Asset Allocation and Asset Pricing in Regulated Markets and Institutions” with Professor Dr. An Chen, University of Ulm, as spokesperson and Prof. Dr. Nicole Bäuerle, KIT, as deputy spokesperson.
This research unit consists of seven professors from six universities:
Prof. Dr. Nicole Bäuerle (KIT), Prof. Dr. Nicole Branger (University of Münster), Prof. Dr. An Chen (University of Ulm, spokesperson), Prof. Dr. Monika Gehde-Trapp (University of Tübingen), Prof. Dr. Antje Mahanyi (University of Duisburg-Essen), Prof. Dr. Melanie Schienle (KIT), Prof. Dr. Caren Sureth-Sloane (University of Paderborn)
The research unit is tackling important questions around risk and uncertainty in decision-making in financial markets and the real economy. Their research will:
More information:
https://www.dfg.de/de/service/presse/pressemitteilungen/2025/pressemitteilung-nr-19
Pressenotiz DFG: Die Forschungsgruppe „Asset Allocation und Asset Pricing in regulierten Märkten und Institutionen“ nimmt die bedeutenden Auswirkungen von Risiko und Unsicherheit bei der Entscheidungsfindung auf den Finanzmärkten und in der Realwirtschaft in den Blick. Im Zentrum der Forschung steht vor allem die Frage, wie sich diese Unsicherheit und das Risikobewusstsein auf die Vermögensallokation und die Preisbildung von Vermögenswerten in regulierten Märkten auswirken. Hierzu sollen nicht nur neuartige quantitative Modelle für regulatorische Unsicherheit entwickelt, sondern auch Messgrößen zur Bewertung dieser Faktoren abgeleitet sowie die mit regulatorischer Unsicherheit verbundenen Auswirkungen auf Märkte und relevante Institutionen analysiert werden.
Professor Dr. An Chen (Ulm University) co-organized the Workshop for Young Mathematicians on Nov 13-15, 2024 in Castle Reisensburg for German Society for Insurance and Financial Mathematics (DGVFM). Eight renowed speakers from academia and practice have provided extremely interesting up-to-date insights in various fields of actuarial science: Prof. Dr. Hansjörg Albrecher (Université de Lausanne), Prof. Dr. Jan-Philipp Schmidt (TH Köln), Prof. Dr. Manuel Rach (Universität St. Gallen), Prof. Dr. Luitgard Veraart (London School of Economics and Political Science), Dr. Dorothee Riemann (Gen Re), Constantin Papaspyratos (Bund der Versicherten), Prof. Dr. An Chen (Universität Ulm) and Prof. Dr. Jörn Saß (RPTU Kaiserslautern-Landau). The topics vary from reinsurance and how to price for a catastrophe cover as well as the challenges of climate change for insurers, dynamic pricing approaches, valuation and design of sustainability-linked bonds, compression of insurance portfolios, to issues related to supervisory and contractual aspects. Around 30 master, bachelor and Ph.D students attended the workshop and enjoyed fruitful discussions with the speakers and the cozy atmosphere of the workshop.

Dr Shihao Zhu (who got PhD at IMW at Bielefeld University under the supervision of Prof. Dr. Giorgio Ferrari and is now a postdoc at IVW at Ulm University) received an Excellence Award for his doctoral thesis entitled "On Some Stochastic Control Models and Related Free-boundary Problems in Insurance Mathematics".
Dr Arne Freimann (who works for ifa - Institut für Finanz- und Aktuarwissenschaften) received an Excellence award for his doctoral thesis on “Pricing, Hedging, and the Roles of Different Market Players in the Longevity Risk Transfer Market” which was supervised by Prof. Dr. Jochen Russ.
Congratulations to both for this fantastic recognition!
Many thanks to the Verein zur Förderung der Versicherungswissenschaft in Hamburg e. V. (VFVH) for supporting young talents in insurance!More information: Link
The 6th Fudan-Ulm Symposium on Finance and Insurance took place at the School of Economics, Fudan University, from September 5 to 6, 2024. Co-hosted by Fudan University’s School of Economics and Ulm University’s Faculty of Mathematics and Economics, with support from the International Finance and Insurance Association (IFIA), this event showcased cutting-edge research across a range of topics including asset allocation, risk management, insurance product design, and more.
This year's symposium was a significant event for the insurance discipline in Fudan and Ulm, attracting participants from various universities and industry professionals, and fostering lively discussions and future collaboration. We look forward to the next edition at Ulm University!
This year's Foundations and Applications of Decentralized Risk Sharing (FADeRiS) conference took place over three days from May 27-29 at Universität Ulm at the beautiful 10th century historic Reisensburg Castle - organized by An Chen (Ulm University) and Peter Hieber (University of Lausanne - HEC Lausanne).
FADeRiS is a conference series dedicated to the theory and practical application of decentralized risk-sharing schemes. Decentralized risk-sharing refers to risk-sharing mechanisms under which the participants in a pool decide to share their risks among themselves, as opposed to classical insurance where an insurance provider takes relevant risks. Examples include peer-to-peer (P2P) insurance, pooled annuity funds or tontines.
Many thanks to all participants for this wonderful conference!
Further information about the conference can be found in the expandable text field.
The first day of the conference featured inspiring presentations on user-friendly metrics for annuitants and the Hashtagethics of mortality risk sharing. The second day focused on various aspects of risk sharing and risk management. Morning sessions covered topics such as efficient Hashtaguncertainty sharing, risk under Hashtagambiguity, and the impact of Hashtagclimate change on natural catastrophe risk pooling. In the afternoon, sessions explored the nuances of Hashtagtontines, including their financial Hashtagguarantees and actuarial Hashtagfairness, as well as the impact of Hashtagmortality dynamics on mutual Hashtagrisk sharing. The third day concluded the conference with presentations on economics and mathematics of risk sharing, as well as belief-neutral HashtagPareto efficiency and robust peer-to-peer risk sharing
In addition to cutting-edge scientific presentations, there were many opportunities for scientific exchange and networking.
The full program, more information about this year's conference and also about the first edition - initiated by Jan Dhaene, Mario Ghossoub, and Michel Denuit - which took place at KU Leuven, can be found here:
Many thanks to all participants for this wonderful conference!
Hansjörg Albrecher (University of Lausanne - HEC Lausanne)
Michail Anthropelos (University of Piräus)
Mücahit Aygün (University of Amsterdam)
Patrick Beiẞner (Australian National University)
Carole Bernard (Grenoble Ecole de Management, Vrije Universiteit Brussel)
Tim Boonen (University of Hong Kong, HKU)
An Chen (Ulm Univerity)
Sascha Günther (University of Lausanne - HEC Lausanne)
Mario Ghossoub (University of Waterloo)
Peter Hieber (University of Lausanne - HEC Lausanne)
Rodrigue Kazzi (KU Leuven)
Roger Laeven (University of Amsterdam)
Felix-Benedikt Liebrich (University of Amsterdam)
Liyuan Lin (University of Waterloo)
Mario Marino (University of Trieste, Italy)
Thai Nguyen (Université Laval, Canada)
Annamaria Olivieri (Università di Parma, Italy)
Patricia Ortega Jiménez (UC Louvain)
Manuel Rach (University of St. Gallen)
Frank Riedel (University of Bielefeld)
Mitja Stadje (University of Ulm)
Julien Trufin (Université Libre de Bruxelles)
Emiliano Valdez (University of Connecticut)
Steven Vanduffel (Vrije Universiteit Brussel)
Ruodu Wang (University of Waterloo)
Morten Wilke (Vrije Universiteit Brussel, University of Ulm)
Shihao Zhu (Ulm University)
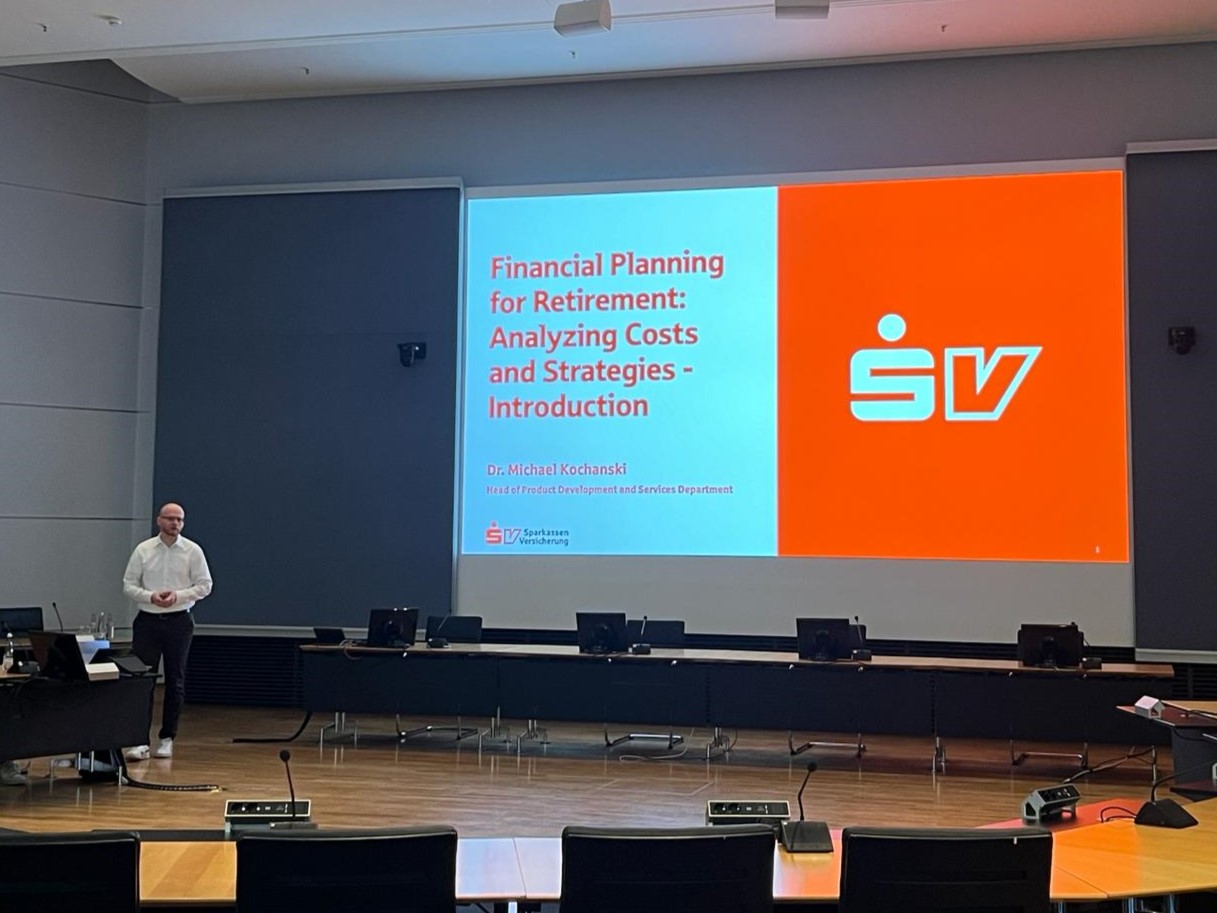
On March 5th 2024 the 15th DGVFM CPD Day took place. The workshop was hosted by SV SparkassenVersicherung in Stuttgart and organized by the HAW-Ausschuss DGVFM (lead: Prof. Dr. An Chen (Universität Ulm) and Prof. Dr. Stefan Weber (Leibniz Universität Hannover)) and Dr. Michael Kochanski (appointed actuary SV SparkassenVersicherung) with the topic "Financial Planning for Retirement: Analyzing Costs and Strategies".
Participants were able to gain insights from research and practice through the following presentations:
The recordings of the presentations will be available soon via actuview: Link
Many thanks to the speakers for their excellent presentations and to SV SparkassenVersicherung for being a great host!

The International Actuarial Association (IAA) has awarded the Chris Daykin Prize 2023 for the best pension relatd paper in the ASTIN Bulletin to Prof. Dr. An Chen and former IVW PhD student Dr. Fangyuan Zhang (joint work with Prof. Dr. Motonobu Kanagawa, EURECOM). The ASTIN Bulletin is one of the most prestigious journals in the field of actuarial science.
In their paper, they analyze a collective defined contribution pension system with multiple overlapping generations. They solve a mathematically complex Bayesian optimization problem and analyze for which persons and under which conditions the welfare can be improved by intergenerational risk sharing. In particular, the results show that intergenerational risk sharing in volatile financial markets leads to an increase in welfare for risk-averse individuals. The analyses are highly relevant for both research and practice, e.g. for pension funds.
Congratulations!

We are very pleased to share three interesting in-depth presentations on current topics with the actuarial community through actuview (the first permanent and international media platform for actuaries):
On the occasion of the on the 75th anniversary of the German Society for Insurance and Financial Mathematics (DGVFM), Prof. An Chen and Prof. Alexander Kling prepared a talk on "What you need at the age of 75: an optimal income for life".
They discuss ideas for innovative retirement products (tontines and tontine-linked products as well as unit-linked annuities) and present some fun facts related to the number 75.
Professor Dr. An Chen (Ulm University) co-organized the Workshop for Young Mathematicians on Nov 28-30, 2022 in Castle Reisensburg for German Society for Insurance and Financial Mathematics (DGVFM), together with Professor Dr. Alfred Müller (University of Siegen). Seven outstanding speakers from academia and practice have provided extremely interesting up-to-date insights in various fields of actuarial science: Prof. Dr. Christoph Belak (TU Berlin), Prof. Dr. Pierre Devolder (UC Louvain), Prof. Dr. Rüdiger Kiesel (University of Duisburg-Essen), Uwe Michel (Executive Vice President and Head of Asia Division of Allianz S.E.), and Dr. Michael Kochanski (Actuary at Sparkassen Versicherung), Prof. Dr. Steven Vanduffel (Vrije Universiteit Brussel), and Prof. Dr. Elena Vigna (University of Turin, Italy). The topics vary from life and pension insurance, asset liability management, model risk, Allianz in Asia, machine learning, to issues related to emerging risks, such as carbon risk. Over 30 master and Ph.D students attended the workshop and enjoyed fruitful discussions with the speakers and the cozy atmosphere of the workshop.

We are very pleased to share two in-depth presentations on current topics here and with the actuarial community through actuview (the first permanent and international media platform for actuaries):


